The IRS tracks cryptocurrency transactions through a combination of third-party reporting from exchanges, blockchain analytics partnerships, and legal tools like John Doe summonses. Starting with tax year 2025, centralized exchanges and brokers are required to file Form 1099-DA reporting your crypto dispositions directly to the IRS. If you traded on a US-based exchange, the IRS already has your data — the question is whether your tax return matches what they received.
In This Article
What Information Do Crypto Exchanges Report to the IRS?
US-based cryptocurrency exchanges report customer transaction data to the IRS through several mechanisms. The most significant change is the Infrastructure Investment and Jobs Act of 2021, which expanded the definition of “broker” to include cryptocurrency exchanges and required them to file information returns.
Coinbase, Kraken, Gemini, and other major US exchanges already issued Form 1099-MISC for users earning over $600 in staking rewards, referral bonuses, or other income. According to IRS guidance in Notice 2023-34 and subsequent rules, brokers must report gross proceeds from crypto dispositions on Form 1099-DA, which functions similarly to the 1099-B used by stock brokerages.
Exchanges also respond to IRS summonses. In 2016, the IRS served Coinbase with a John Doe summons seeking records on all customers who conducted transactions between 2013 and 2015. A federal court approved a narrowed version covering accounts with over $20,000 in transactions. According to court records, Coinbase ultimately turned over data on approximately 13,000 customers. Similar summonses have targeted Kraken and Circle.
| Reporting Method | What It Covers | Who Files It | Threshold |
|---|---|---|---|
| Form 1099-DA | Gross proceeds from crypto sales and exchanges | Exchanges and brokers | All transactions (phased implementation) |
| Form 1099-MISC | Staking rewards, referral income, airdrops | Exchanges paying income | $600+ |
| Form 1099-K | Payment transactions (P2P platforms) | Payment processors | $600+ (current threshold) |
| John Doe summons | All account records for a class of taxpayers | IRS via federal court order | Set by court |
| Individual summons | Specific taxpayer records during audit | IRS directly | N/A |
For a complete guide on your filing obligations, read our IRS cryptocurrency tax guide.
How Does the IRS Use Blockchain Analytics?
The IRS Criminal Investigation division (IRS-CI) contracts with blockchain analytics firms to trace cryptocurrency transactions across public blockchains. Chainalysis is the primary vendor. According to federal procurement records, the IRS has spent tens of millions on Chainalysis licenses since 2015.
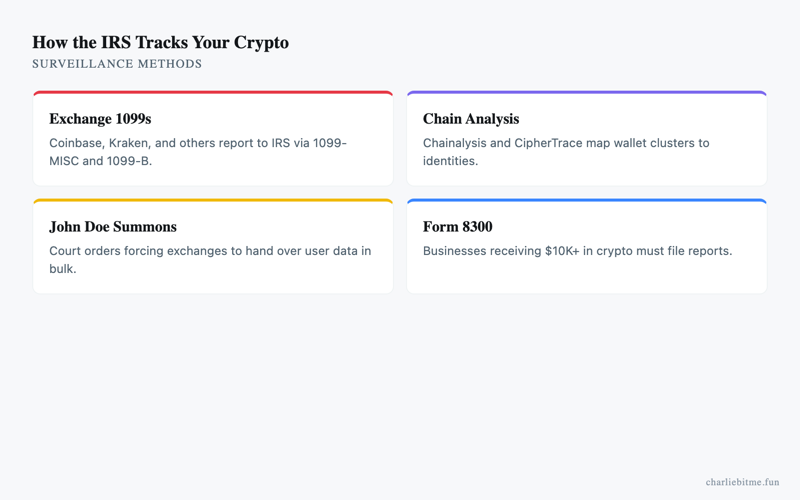
Chainalysis Reactor allows investigators to link wallet addresses to real identities by clustering transactions and matching on-ramp/off-ramp points with exchange KYC data. When you deposit crypto to Coinbase, that deposit address becomes associated with your identity. Chainalysis maps the flow of funds backward through every wallet that sent crypto to that address.
The IRS also contracted with Integra FEC for tracing privacy-focused cryptocurrencies. According to contract records published on USAspending.gov, the IRS sought tools specifically capable of tracing Monero and Lightning Network transactions. While these privacy technologies make tracing harder, the IRS has shown willingness to invest in breaking those barriers.
IRS-CI has publicly stated that blockchain analytics played a central role in several high-profile cases, including the recovery of $3.6 billion in Bitcoin stolen from Bitfinex in 2016. According to the Department of Justice press release, investigators traced the funds through thousands of transactions over six years using chain analysis tools.
What Triggers an IRS Crypto Audit?
The IRS uses several signals to identify taxpayers who may have underreported cryptocurrency income. The most common triggers involve discrepancies between exchange-reported data and your tax return.
Since 2019, the IRS has included a cryptocurrency question on Form 1040 asking whether you received, sold, exchanged, or disposed of any digital assets during the tax year. According to IRS Commissioner statements, answering “No” when exchange records show activity is treated as a red flag.
Other audit triggers include: receiving a 1099 from an exchange but not reporting corresponding income; large deposits to bank accounts from crypto exchange withdrawals without reported gains; and lifestyle indicators inconsistent with reported income. The IRS Compliance Campaign specifically targeting virtual currency launched in 2018 and remains active.
The IRS sent over 10,000 letters (CP2000, 6173, 6174, 6174-A) to cryptocurrency holders in 2019 alone, warning of potential underreporting. These letters referenced exchange data the IRS already possessed. For reporting your crypto trades properly, see our guide on reporting DeFi income on your tax return.
Can the IRS Track DeFi and DEX Transactions?
Decentralized exchanges and DeFi protocols do not collect KYC information and do not file 1099 forms. This creates a gap in third-party reporting. However, every transaction on a public blockchain like Ethereum is permanently recorded and traceable.
The IRS can trace DeFi activity by following the chain of transactions from a known identity point. If you withdrew ETH from Coinbase (where your identity is verified) to a personal wallet, then swapped tokens on Uniswap, the IRS can potentially connect that Uniswap activity to you through Chainalysis clustering and the Coinbase withdrawal record.
The Treasury Department’s proposed regulations from 2023 attempted to extend broker reporting requirements to DeFi front-ends. When I last checked, the final implementation timeline and scope were still being debated. Regardless of regulatory status, the on-chain data is permanent — the IRS could retroactively analyze DeFi transactions if it obtains your wallet addresses through other means.
My view: relying on DeFi’s lack of KYC as a tax avoidance strategy is shortsighted. The IRS has demonstrated both the technical capability and legal willingness to trace decentralized transactions. The cost of voluntary compliance is far lower than the penalties for getting caught. See also whether airdrops create tax obligations.
What Are the Penalties for Not Reporting Crypto?
Penalties for underreporting cryptocurrency income range from accuracy-related penalties to criminal prosecution. The severity depends on whether the IRS views the underreporting as negligence or willful evasion.
Accuracy-related penalties under IRC Section 6662 add 20% of the underpaid tax. If the understatement is substantial (exceeding 25% of the tax shown on the return), the penalty applies automatically unless you can demonstrate reasonable cause.
Willful failure to report crypto income can result in civil fraud penalties of 75% of the underpaid tax, plus criminal prosecution carrying fines up to $250,000 and imprisonment up to five years under IRC Section 7201 (tax evasion). The IRS has secured criminal convictions specifically for cryptocurrency tax evasion. Read our research methodology for how we verify these legal standards.
Frequently Asked Questions
- Does the IRS know about my crypto if I only used a foreign exchange?
- Foreign exchanges with US customers are increasingly subject to information-sharing agreements. FATCA (Foreign Account Tax Compliance Act) requires foreign financial institutions to report US account holders. Exchanges like Binance (via Binance.US) and others have cooperated with IRS requests. If you transferred crypto between a foreign exchange and a US-based exchange, the chain of transactions is traceable.
- Can the IRS track Bitcoin transactions?
- Yes. Bitcoin transactions are recorded on a public blockchain visible to anyone. Chainalysis and similar firms specialize in de-anonymizing Bitcoin transactions by clustering wallet addresses and matching them to exchange KYC records. The IRS has used these tools to successfully trace billions in Bitcoin across complex transaction chains.
- What is a John Doe summons?
- A John Doe summons is an IRS legal tool authorized by IRC Section 7609 that allows the agency to request records from a third party about an unnamed class of taxpayers. The IRS must obtain court approval and demonstrate a reasonable basis for believing the class has failed to comply with tax law. These have been used against Coinbase, Kraken, and Circle.
- Should I amend past returns if I did not report crypto?
- Consult a tax attorney or CPA experienced in cryptocurrency taxation. Filing amended returns (Form 1040-X) and paying owed taxes with interest can potentially reduce penalties. Voluntary disclosure before the IRS contacts you generally results in better outcomes than waiting to be caught. This is not legal advice.
This article is for informational purposes only and does not constitute tax or legal advice. Tax laws are complex and vary by situation. Consult a qualified tax professional or attorney for guidance specific to your circumstances.
Sources
- IRS — Virtual Currency Guidance — Official IRS cryptocurrency tax resources (checked August 2026)
- IRS — FAQ on Virtual Currency — Frequently asked questions on crypto reporting (checked August 2026)
- Chainalysis — Blockchain analytics provider (checked August 2026)
- Department of Justice Press Releases — Crypto enforcement case announcements (checked August 2026)
- USAspending.gov — Federal contract records for IRS analytics procurement (checked August 2026)